Market volatility can make an established investment plan feel less certain. Account balances fluctuate, headlines compete for attention, and commentary offers conflicting explanations about what comes next. Even investors who expected occasional declines may find themselves questioning decisions that previously felt appropriate. The challenge is maintaining a clear basis for decisions while conditions change.
A portfolio should respond to meaningful developments in your circumstances and investment needs. When short-term market movements become the main reason for making changes, however, it becomes harder to maintain a consistent approach. Preparing for those moments can help you evaluate what deserves action and what deserves patience.
Understand What Consistency Actually Means
Consistency means applying a clear decision process across different market conditions. It doesn’t require holding every investment forever or maintaining an allocation that no longer suits your needs. A plan should evolve as your circumstances change. Someone approaching retirement may need a different approach from the one they followed while accumulating savings. A business sale, reduced income, or new family responsibility can also justify adjustments. Those decisions connect portfolio changes to a financial purpose.
By comparison, repeatedly switching strategies because markets have risen or fallen can leave the portfolio without a clear direction. The question is whether the proposed change responds to your needs, new evidence about an investment, or the discomfort of watching prices move.
Reconnect the Portfolio With Its Purpose
During volatility, the account balance can become the focus. Revisiting what the money is intended to support helps restore context. Retirement income, a home purchase, and a child’s education involve different timelines and demands. Consider a household saving for retirement while also preparing to help a child with tuition next year. Both goals matter, but the money serving each goal may require a different approach. A market decline has different implications for an upcoming payment than for savings intended to remain invested for many years.
Reviewing those purposes makes the discussion more specific. Instead of asking whether markets feel too risky, consider whether the investments supporting each goal still reflect when the money will be needed and how much loss the household can absorb.
Plan for Withdrawals Before They Become Urgent
An expected withdrawal can become stressful if the money is tied up in investments that have recently declined. Identifying upcoming spending needs gives you time to decide how to fund those expenses. For a retiree, this might involve reviewing planned withdrawals alongside pension income and other available resources. For a family, it could mean identifying funds needed for tuition, renovations, or a major purchase. Accessible savings and investments selected for nearer-term needs can provide flexibility when markets fluctuate.
No single amount works for every household. The appropriate approach depends on expenses, income reliability, withdrawal timing, and the overall plan. The useful step is to make those decisions before a market decline turns an expected payment into an urgent portfolio question.
Use Reviews to Put Headlines in Context
Financial news provides information, but it does not know your objectives or circumstances. A headline about economic growth or interest rates may matter to your investments without requiring an immediate trade. An agreed review schedule creates an opportunity to assess developments together. Between reviews, you can identify situations that warrant earlier attention, such as a significant change in income, an unexpected expense, or material news affecting a holding.
When a headline raises concern, write down the specific question it creates. Does it affect the investment’s prospects? Does it change your expected cash needs? Has it revealed exposure you did not understand? Turning a reaction into a defined question makes the next conversation more useful.
Check Whether the Investment Mix Has Drifted
Market movements can change a portfolio even when you make no trades. Investments that perform differently grow or shrink as a proportion of the total, potentially moving the allocation away from its intended balance. Rebalancing helps address that drift. Depending on the circumstances, it may involve directing contributions towards underrepresented holdings or reducing positions that have become too large. The decision should account for costs, potential tax consequences, and any restrictions.
A review schedule or agreed allocation ranges can guide when to assess rebalancing. This gives you a reason to adjust that connects to the portfolio’s design. It also provides a basis for explaining why a change is appropriate even when the surrounding market commentary points in several directions.
Keep Contributions Connected to Your Circumstances
During a decline, continuing to invest can feel uncomfortable. An investor may pause contributions until the outlook improves, only to discover months later that the pause has become indefinite. Regular contributions should remain connected to affordability and financial priorities. If income and cash needs are unchanged, review whether stopping contributions would move savings away from the plan. If employment becomes uncertain or essential expenses increase, adjusting contributions may be appropriate.
The distinction matters. A household dealing with reduced income has a different decision to make from one reacting solely to falling prices. A consistent process considers both the investment environment and the practical demands on the money before deciding what to change.
Recognize When the Plan Needs Reassessment
Volatility can reveal that an investor’s expected comfort with risk differs from their actual experience. Persistent worry, repeated urges to sell everything, or difficulty meeting spending needs deserve attention. These experiences may indicate that the allocation, cash arrangements, or assumptions need review. Staying aligned with a plan requires understanding whether it remains suitable. Discussing concerns early creates an opportunity to make considered adjustments rather than waiting until pressure becomes overwhelming.
It is also useful to distinguish disappointment from a change in capacity. A lower balance may be upsetting without affecting your ability to meet obligations. Alternatively, a modest decline could matter considerably when you need money soon. The response should reflect those circumstances.
Give Your Next Decision a Clear Foundation
Before making a significant change during volatility, explain what you intend to accomplish and how the adjustment supports your goals. Consider its effect on risk, future withdrawals, and the rest of the portfolio. A decision you can explain clearly is easier to review later.
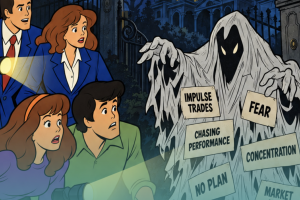
Our comic book, The Scariest Mistakes Investors Make and How to Avoid Them, follows investors as they learn to recognize the habits behind their financial uncertainty. Their investigation reveals why a clear process matters when emotions and headlines compete for attention.
The Brook Wagman Wealth Management & Planning team can help you review your allocation, upcoming needs, and approach to market changes. Read the comic book, then consider whether your plan gives you a clear basis for the next decision.